Key takeaways:
- Most construction risk comes in through four gaps: subcontractors who start work before their insurance is vetted, certificates that lapse because nobody sent the renewal, companies working on wrap-up projects without being enrolled, and hazards that get spotted but never assigned to anyone.
- Live jobsite data closes those gaps at the gate and on the deck. Uninsured or unenrolled companies get stopped at orientation or the turnstile, and every observation gets an owner and a clock.
- Carriers are starting to use the same data. Instead of visiting a client's jobsites in rotation, a carrier can watch a portfolio's safety scores, get an alert when one drops, and send its risk engineers to the project that's slipping.
Traditional construction risk management runs on two things: lagging numbers, such as past claims and experience modification rates, and periodic site visits. Both look backward. A loss-control engineer who visits each of a client's projects once a quarter sees a site on one day out of ninety. Meanwhile, the risk builds daily: a subcontractor whose insurance nobody checked, a deck where the guardrail netting keeps coming down, a project that's fallen weeks behind on its paperwork.
This guide covers where construction risk actually hides, how live jobsite data closes those gaps, and how insurers are starting to use that data, drawing on SafetyClerk co-founder Stefano Braganti's work with contractors, brokers, and carriers.
Where Construction Risk Hides
The vetting gap. The insurance gap Stefano sees most often comes from a company that shows up before anyone vetted it. A project manager asks a subcontractor to start, the crew arrives for orientation, and the superintendent assumes that if the PM sent them, the paperwork is done.
"Most of the time, there's a gap between the work and the vetting from the procurement department."
The renewal gap. When a certificate of insurance does lapse mid-project, the coverage usually hasn't actually ended. More often, the subcontractor never sent its annual renewal.
The enrollment gap. On wrap-up projects, coverage depends on enrollment, and enrollment has to happen before the work starts. A company that isn't enrolled is working outside the program.
The paperwork gap. Every subcontractor brings 20 to 30 documents to a project, depending on its trade: a W-9, insurance, a safety manual, a site-specific safety plan, procedures for specific hazards, a fall protection plan. Then come the daily records: pre-task plans, equipment checklists, hot work permits, access control, and permits to remove temporary netting. Stefano remembers what that looked like by hand from his years at a construction manager:
"You were doing probably 20 percent of it, and you were still working six hours a day on paperwork."
The observation gap. Someone notices the hazard, writes it up, and sends a report at the end of the day. A week later, someone walks the site again to see whether it was fixed. In between, nobody owns it.
Closing the Insurance Gap at the Gate
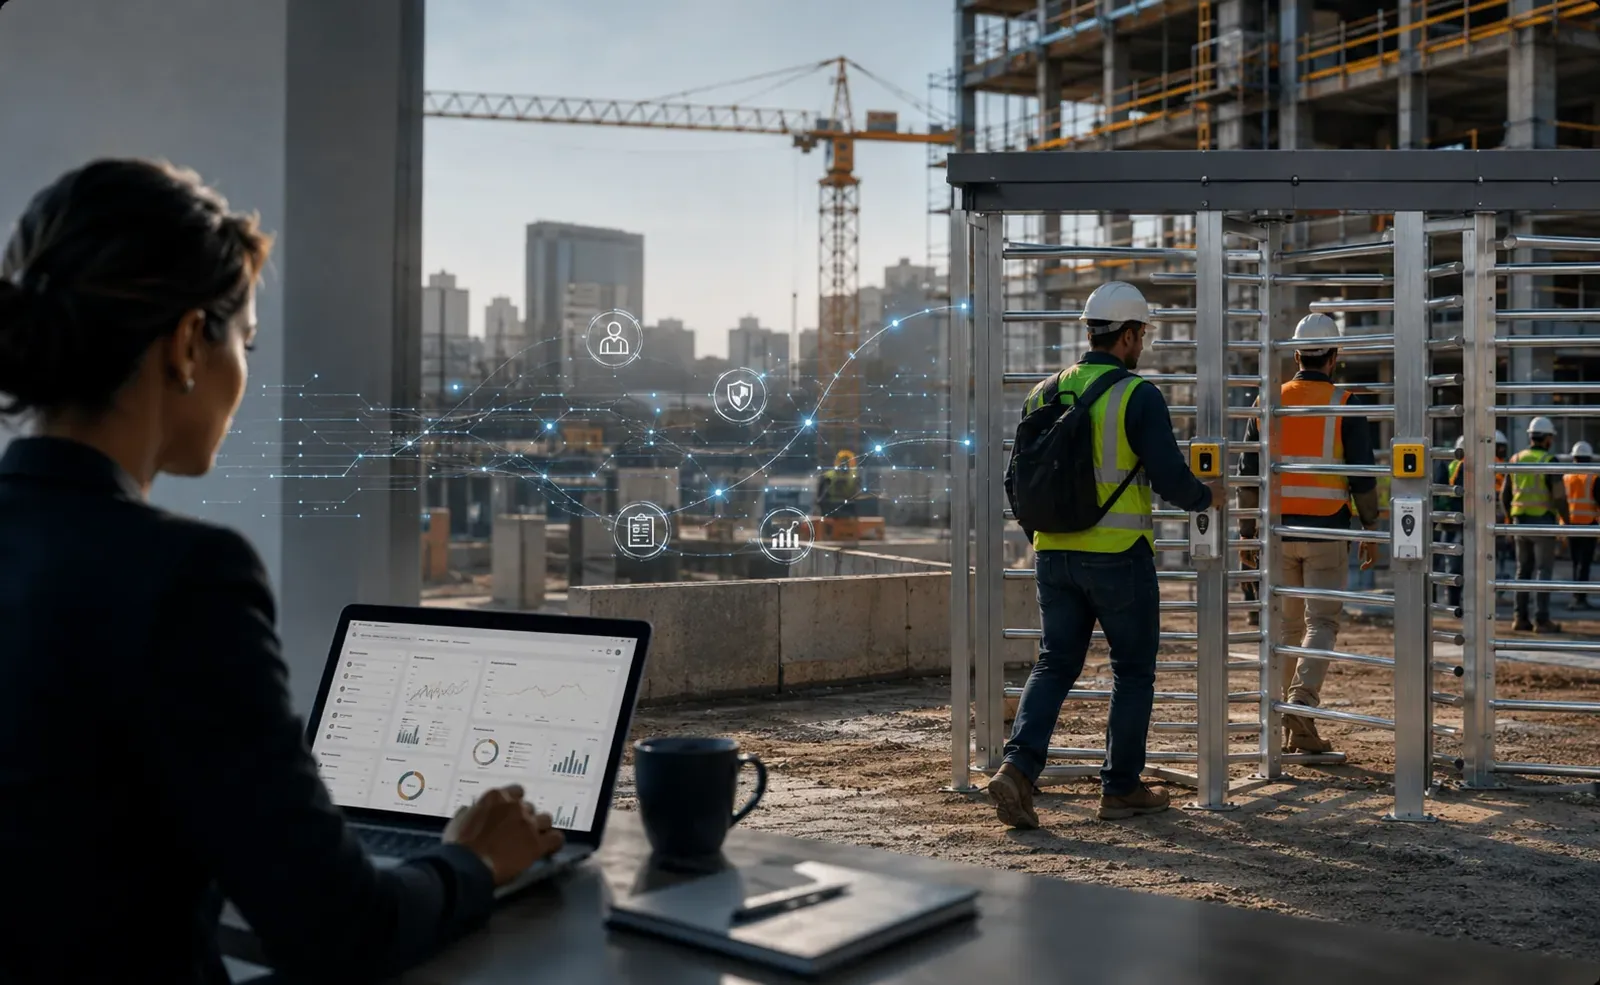
The fix for the vetting and renewal gaps is the same. Insurance status has to follow the worker to the gate.
SafetyClerk tracks each subcontractor's certificates of insurance from onboarding. The insurance data follows the company from jobsite to jobsite, and the system sends 30 days' notice before a policy expires. It connects to the turnstile, where contractors choose how strict to be:
- Block: workers from a company with a lapsed or missing certificate can't get in.
- Notify: workers can enter, and the superintendent is alerted right away.
Stefano recommends the stricter setting, for a practical reason:
"If you block people off, they get you the renewal certificate within minutes, not days."
The vetting gap gets caught earlier, at orientation. The first time a worker from an unknown company shows up for orientation, SafetyClerk tells the superintendent the company isn't in the project's records, so it hasn't been approved from an insurance standpoint. The superintendent checks with the office before the crew starts work. According to Stefano, that's where most liability gaps get caught and closed.
Wrap-Up Programs: Only Enrolled Contractors on Site
On large projects, insurance often comes through a wrap-up program. A wrap-up is a consolidated program, typically providing workers' compensation and general liability coverage to every enrolled contractor and subcontractor for work at one project site. When the owner sponsors it, it's an owner-controlled insurance program (OCIP). When the general contractor sponsors it, it's a contractor-controlled insurance program (CCIP). Participation is mandatory, but it isn't automatic. Every contractor and subcontractor, at every tier, has to be reviewed for participation before starting work at the site.
That's the enrollment gap, and it's hard to police by hand on a project with dozens of subcontractors and hundreds of workers. SafetyClerk's wrap-up tools work like a virtual gate:
- Worker companies are checked automatically against the program administrator's approval.
- Non-enrolled workers are blocked at the turnstile, or the superintendent can't complete their orientation.
- Companies that fall out of compliance mid-project are flagged and blocked.
SafetyClerk integrates with major wrap-up program administrators and pulls their daily enrollment reports into the system.
The same data supports the financial side of a wrap-up:
- Payroll. SafetyClerk compares the payroll hours subcontractors report against actual turnstile hours, flagging inconsistencies and inflated hours that can increase insurance exposure, and breaks reporting down by class code.
- Contract spend. It tracks monthly subcontractor spend against the original contract amount, so program sponsors can anticipate additional premium due.
- Claims and loss ratio. It tracks claims against the overall program amount each month, and analyzes loss ratios to show whether a wrap-up or traditional insurance is more cost-effective for each subcontractor.
Leading Indicators That Show Risk Building
Claims and experience modification rates tell you what already happened. OSHA's recommended practices for construction safety programs point the other way, toward leading indicators, such as whether corrective actions get completed on time.
Observations are where most of those indicators come from, and Stefano says the way they're set up decides whether they're useful. Four things matter:
Record positive observations too. Almost every tool supports flagging something wrong. Stefano's case for flagging something done right:
"It should be a given that a scaffold is set up in a safe way. But by highlighting it through a positive observation that gets broadcast to the entire jobsite, you actually increase the chance that people do good things."
He says SafetyClerk has seen negative observations go down on projects that also use positive observations.
Use the same categories on every site. If every project sets up its own categories, the data can't be compared at the company level, and you can't benchmark one jobsite against another.
Assign it to the responsible party right away. Don't save it for an end-of-day report. When the safety manager sees broken netting on a guardrail, the observation goes straight to the company responsible for that netting. They get notified, fix it, and close it with a photo.
"There's a rush from the accountable party to fix it, because they can see it's in their court."
On SafetyClerk, if an assigned observation isn't resolved the same day, the system starts emailing the subcontractor's office the next day. It also measures how long each company takes to close observations, which is exactly the kind of leading indicator OSHA's recommended practices describe.
Document it even when it's fixed on the spot. A deficiency fixed while the safety manager is standing there still belongs in the record. Every observation rolls up into a main category, such as falls, electrical, or struck-by, so trends show up across the site. When a trend appears, SafetyClerk can suggest a toolbox talk for the trade that's driving it. A run of fall protection observations for one company, for example, prompts fall prevention training for that company.
How Carriers Use SafetyScore
SafetyScore pulls those signals together into a score for every worker, crew, company, and project. SafetyClerk's own comparison is telematics in auto insurance: live operational visibility into jobsite risk, before claims happen.
Here's how Stefano describes a carrier using it:
- A portfolio view. The carrier sees every insured client in one dashboard and watches for scores trending down.
- Thresholds and alerts. The carrier sets a threshold, say 55. When a client's company score drops below it, both the client and the carrier get alerted.
- Drilling into the project. A whole company rarely slips at once. Say it's an HVAC contractor with eight active projects. The carrier can see which project is pulling the score down, whether that's a site behind on paperwork, a recent incident, or something else.
- Sending the risk engineers where the risk is. Most loss-control programs visit sites in rotation: project one this month, project two next month, down the list. With a live score, the carrier sends its risk engineering team to the project that's slipping and works with the client to bring compliance back up.
SafetyClerk calls it "targeted loss control": replacing random site visits with precise interventions. Carriers can also use the live operational indicators alongside historical loss data in underwriting, and pull time-stamped records instantly during a claim investigation.
What GCs Get From the Same Data
The data a carrier watches is the same data a GC can use to manage its own risk:
- Subcontractor safety insights. Track the safety performance of every subcontractor on site, and use the data to choose the safest subcontractors for the next project.
- Crew benchmarking. Know whether a subcontractor is sending its best crews to your project, or its worst.
- Worker prequalification. Identify and vet high-risk workers before they reach the project.
- Real-time comparisons. Compare safety performance across sites, and get alerts when it falls below the level you set.
For subcontractors, it works the other way. A strong record becomes proof of safety engagement for the GCs they work for, and a set of safety and productivity numbers they can show when they bid.
Questions to Ask Construction Risk Management Software
Whatever system you're considering, ask:
- Does insurance status reach the turnstile, so a lapsed or missing certificate can stop a worker at the gate?
- Does it catch unknown companies at orientation, before they're on the deck?
- On wrap-up projects, does it check enrollment against the program administrator's records automatically?
- Do observations use the same categories on every site, so you can compare projects?
- Does every observation get assigned to the party responsible for fixing it, with a clock and an escalation if it's not closed?
- Does it record positive observations as well as hazards?
- Can you see risk building, by crew, subcontractor, and project, before an incident?
- Can your carrier or broker see the same picture, with your permission?
How SafetyClerk Helps
Insurance at the gate. SafetyClerk's insurance management tracks every subcontractor's certificates of insurance, gives 30 days' notice before policies expire, and works with the turnstiles to keep out workers from non-compliant companies.
Wrap-up programs. The wrap-up tools enforce program enrollment at the gate, and connect administrator, carrier, and jobsite data for payroll, contract spend, claims, and loss ratios.
Observations and alerts. Observations get an owner, a clock, and an escalation. SafetyScore compares safety performance across workers, crews, companies, and projects, with live alerts when a score drops.
All of it runs on the same records workers create every day: orientations, pre-shifts signed at check-in, toolbox talks, and inspections.
Frequently Asked Questions
What is construction risk management software?
Software that tracks the signals behind construction losses, such as insurance compliance, safety observations, corrective actions, certifications, and incidents, and turns them into alerts and scores. Contractors use it to manage subcontractors and jobsites. Insurers use it to target loss control and inform underwriting.
How do insurance carriers use jobsite safety data?
Carriers can watch a portfolio of insured contractors in one dashboard, set alert thresholds, and see which client, and which project, is driving risk up. That lets them send risk engineers where the risk is, instead of visiting every site in rotation.
Can a safety score lower my insurance premium?
It can be part of the conversation, but don't count on it alone. SafetyClerk has a carrier program that ties a premium discount to keeping a SafetyScore above a threshold. Stefano says that as of October 2026, he isn't aware of a broker lowering a premium based on a score by itself.
How is SafetyScore different from EMR or TRIR?
An experience modification rate and a total recordable incident rate are built from past claims and injuries. SafetyScore is built from what's happening on the jobsite now, including observations, certifications, and compliance, so it can show risk building before it becomes a claim.
What is a CCIP or OCIP?
A wrap-up insurance program covering enrolled contractors on a project, typically for workers' compensation and general liability. An OCIP is sponsored by the owner, and a CCIP by the general contractor. Every contractor has to be reviewed for enrollment before starting work at the site.
How do you stop uninsured subcontractors from working on site?
Tie insurance status to site access. Block entry at the turnstile when a certificate lapses or is missing, and catch unknown companies at orientation, before their crews start work.
This article provides general information about construction risk management and insurance and isn't insurance or legal advice. Coverage terms vary by policy and program, so confirm details with your broker or program administrator.
See your jobsite risk the way your carrier could. A SafetyClerk demo takes 30 minutes. Book a Demo




 Review us on G2
 Review us on Capterra